What is the baseline market overview for the Print Advertising Distribution Market?
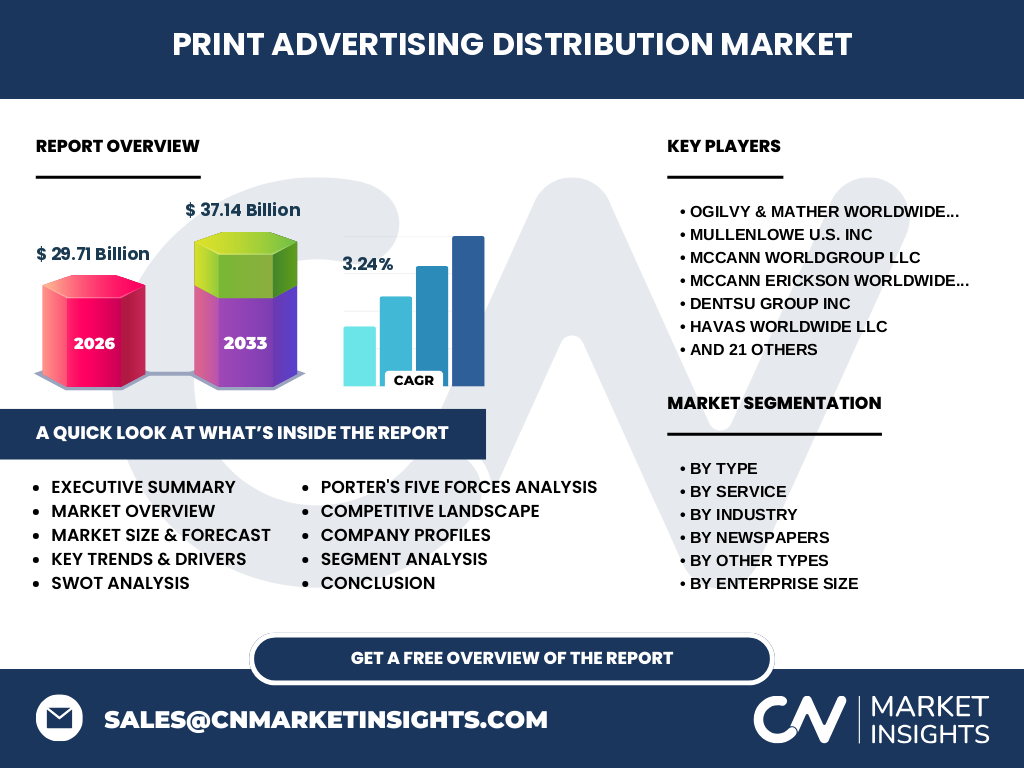
Our analysis indicates that the Print Advertising Distribution Market size reaches 29.71 Billion in 2026. This sector encompasses the physical logistics and strategic dissemination of marketing collateral—ranging from newspapers to door-to-door flyers—serving as an indispensable tactile channel for retail and financial institutions navigating digital saturation.
What are the core structural growth drivers and restraints shaping the Print Advertising Distribution Market?
Growth is propelled by high consumer trust in tactile media, offset by stringent environmental regulations regarding paper waste and volatile pulp raw material costs. Logistical hurdles in urban last-mile delivery further constrain margins, forcing operators to optimize routing for circulars and direct mail.
What emerging trends and distribution patterns define the Print Advertising Distribution Market industry trends?
The shift toward hyper-localized sample direct distribution services and targeted flyer campaigns stands out. Agencies are leveraging geospatial data to optimize door-to-door delivery, ensuring retail catalogs reach high-density demographic clusters with minimal logistical waste.
How did the COVID-19 pandemic reshape the Print Advertising Distribution Market analysis?
Pandemic lockdowns initially fractured supply chains and halted retail circulation. However, the post-pandemic recovery trajectory shows a resilient rebound as brick-and-mortar retailers re-engage physical mailers to drive foot traffic, stabilizing the sector toward its 2027-2033 expansion phase.
Competitive Benchmarking: Who dominates the Print Advertising Distribution Market landscape?
Market concentration is high among global holding companies like WPP plc, Omnicom Group Inc, and Publicis-affiliated networks. These giants integrate physical distribution with omnichannel campaigns, leveraging scale to negotiate favorable paper procurement rates and postal partnerships.
Executive Summary of the Print Advertising Distribution Market research report
Our comprehensive research values the market at 29.71 Billion in 2026, advancing at a 3.24% CAGR to hit 37.14 Billion by 2033. Retail and financial sectors remain the primary revenue anchors, demanding sophisticated door-to-door and catalog distribution strategies.
What is the projected market forecast for the Print Advertising Distribution Market from 2027 to 2033?
The data projects steady expansion from 37.14 Billion through 2033, driven by a reliable 3.24% CAGR. This steady trajectory reflects renewed advertiser confidence in physical touchpoints, particularly for high-impact promotional inserts and targeted coupon distribution.
How is the Print Advertising Distribution Market segmented across types, services, and industries?
Segmentation spans Newspapers, Magazines, Posters, and Banners by type; specialized services like Advertising Material Direct Distribution and Flyer Delivery; and end-use verticals including Retail, Electronics, Insurance, and Finance across both SMEs and large enterprises.
Geographic distribution and regional performance in the Print Advertising Distribution Market
Regional performance varies based on postal infrastructure maturity and local municipal regulations governing out-of-home advertising. Developed urban centers exhibit strong demand for specialized flyer and catalog dissemination, whereas emerging economies focus on expanding national newspaper networks.
In-depth regional review of logistics and regulatory constraints
Strict paper-disposal laws in Western markets require distributors to utilize certified recyclable substrates. Meanwhile, dense Asian metropolitan hubs rely heavily on high-speed door-to-door distribution networks to service massive retail consumer bases efficiently.
Strategic positioning of leading enterprise players in the Print Advertising Distribution Market
Industry leaders such as Ogilvy & Mather, McCann Worldgroup, and Dentsu Group combine creative ad design with precise logistical execution. They partner with specialized regional couriers to guarantee compliant, targeted distribution for major retail brands.
Porter's Five Forces Analysis of competitive pressures
Supplier power remains moderate due to consolidated paper mills, while buyer power is high among major retail conglomerates. Threat of substitution stems from digital channels, yet physical distribution retains an unshakeable edge in local demographic penetration.
SWOT Analysis highlighting internal capabilities and external market forces
Key strengths include high engagement rates for physical mailers. Weaknesses involve rising fuel and paper costs. Opportunities lie in tech-enabled hyper-local targeting, while threats include aggressive digital advertising spend reallocation.
Value Chain Analysis from raw material procurement to end-user delivery
The value chain flows from pulp mills and paper manufacturers through creative agencies like Wieden+Kennedy or BBDO, down to specialized last-mile couriers executing door-to-door drop-offs for retail and telecom end-users.
High-potential investment insights and strategic recommendations
Investors should target firms integrating green logistics with programmatic print planning. Companies focusing on automated sample and coupon direct distribution services for the retail sector offer the most attractive yield potential.
Conclusion and key takeaways for strategic decision-makers
The Print Advertising Distribution Market proves that physical media remains a vital component of holistic marketing mixes. With a stable valuation scaling toward 37.14 Billion, adaptation and logistical precision are paramount for sustained profitability.
How was the baseline data triangulated in the research methodology?
Our methodology triangulates trade registry data, postal authority volume reports, and primary stakeholder interviews with executives across major holding groups like Interpublic Group and Omnicom, cross-referenced against macroeconomic retail indices.
What are the coverage parameters and limitations within the scope of the report?
This report covers global physical advertising distribution channels from 2026 through 2033. Limitations include localized postal tariff shifts and unquantified informal black-market flyer distribution networks operating in developing urban economies.
Recent developments, partnerships, and strategic moves across the industry
Major agencies continue forming strategic alliances with green-logistics providers to reduce carbon footprints. Recent corporate announcements highlight investments in automated sorting facilities and geotargeted software to enhance flyer and catalog delivery efficiency.